Agribusiness CFO, Kansas
Cash planned a season ahead, not a harvest behind.
An agribusiness CFO for Kansas equipment dealers, grain and seed businesses and large family operations: seasonal working capital, operating lines, equipment finance and commodity exposure, planned before the season starts.
The ag year, in three lines
- Inputs are paid in spring. Revenue arrives in the fall.
- The operating line is up for renewal and the bank wants a projection.
- Prices moved and nobody has rerun the numbers.
Or call (316) 555-0179. Monday to Friday, 8:00 am to 5:30 pm.
The seasonal curve
Twelve months, one line.
Most ag businesses spend months drawing on the line and months paying it down. Knowing the low point, and when it comes, is the plan.
What we set up
Three things before planting.
- 01
A seasonal forecast
Monthly for the year and weekly through the tight months, built on the same model as our 13-week forecast.
- 02
The line, sized
Peak borrowing need and the borrowing base calculated before renewal, not during it.
- 03
Price scenarios
What a move in commodity prices or input costs does to margin and to the line.
Lender lines
What your ag lender wants to see.
Operating lines and equipment notes get renewed on the strength of the projection. We prepare it, the same way we build a loan package.
- A twelve-month projection with the seasonal low point marked
- Borrowing base: receivables, inventory and grain on hand
- Equipment notes and leases scheduled
- Covenant tests run before the bank runs them
- A plain summary of what changed since last year
Fair questions
What operators ask us.
“Our ag lender already does our projections.”
Then you are seeing the bank's view of your business. We build yours, so the conversation at renewal starts from your numbers.
“Do you give marketing or hedging advice?”
No. We show what price moves do to cash and margin. Marketing and hedging decisions stay with you and your advisers.
The detail
Dealers, elevators and family operations.
Equipment dealers carry inventory that has to be floored and financed. Grain and seed businesses swing on receipts and settlement. Large family operations often run several entities with shared debt. Each gets a forecast built for how its year actually runs.
For family operations thinking about the next generation, the same clean reporting supports a transition or a sale. See exit readiness, and the published bands on pricing.
Who leads it
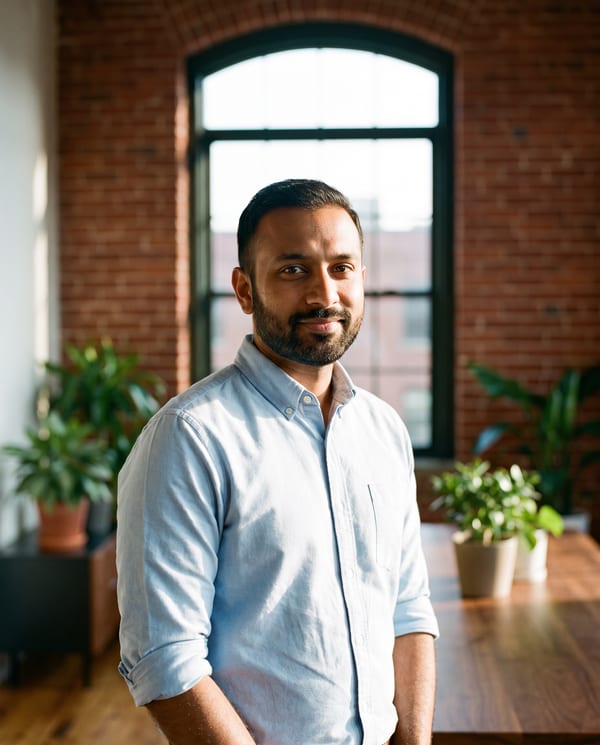 Theo BanerjeePartner, Forecasting and Lender Packages
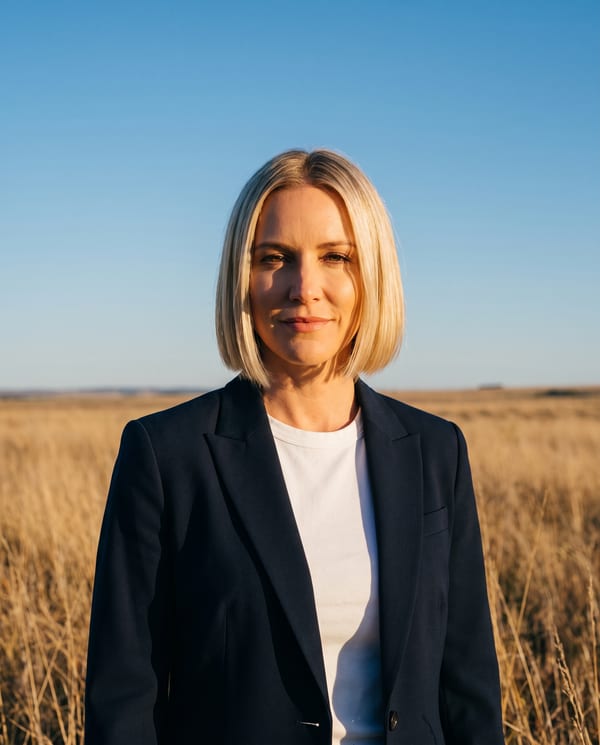 Lena LindqvistFounding Partner, Fractional CFO
Theo builds the seasonal forecast and the lender package. Lena runs the planning meetings.

Where we work
Old Town first, then the whole metro.
We work from 317 N Rock Island St, Suite 210, Wichita, KS 67202, on the second floor of a restored brick warehouse. The first meeting is at your shop, your yard or your office, anywhere in the Wichita metro.
- Old Town
- Delano
- College Hill
- East Wichita
- Derby
- Andover
- Maize
- Haysville
- Park City
- Bel Aire
- Goddard
- Newton
- El Dorado
- Kansas, by video
Q01What does an agribusiness CFO do?
Plans seasonal working capital, sizes and renews operating lines, builds the case for equipment finance, and shows what commodity and input price moves do to the year.
Q02Do you work with farms or only dealers?
Both: equipment dealers, grain and seed businesses, and large family operations with several entities.
Q03Do you prepare farm tax returns?
No. Your CPA prepares the returns. We work alongside them and give them clean monthly books.
Q04When should we start before renewal?
At least two months before the operating line renews, so the projection is ready before the bank asks.
Q05Do you visit the operation?
Yes. The first meeting is at your yard, your dealership or your office, anywhere in the Wichita metro and by arrangement across Kansas.

Next step
Know the low point before the season starts.
The 13-week cash review is a fixed $1,950: your bank data in, a working model and your runway number out, reviewed with a partner in a two-hour session. Three details in the form, or one call.